How many credit cards do travelers really need?
Find out the ideal number of credit cards travelers should have to boost rewards, cut down on fees, and create a more efficient wallet.
The Smart Traveler’s Credit Card Setup
An enticing myth is spreading among frequent travelers in the U.S.
You see it in “wallet setup” videos, points-and-miles communities, and influencers flaunting piles of metal credit cards as if they were trophies of status.
The message implied is always consistent:
Owning more cards means you appear more financially savvy.
We disagree—and we’ll be frank:
The majority of American travelers hold too many cards, incur needless annual fees, and mistake complexity for smart strategy.
If you have to consult a spreadsheet every time you pay for dinner in Chicago, book a hotel in Miami, or purchase a flight to London, your approach isn’t working.
That’s not a strategy. It’s just having too much, disguised as optimization.
Is minimalism worth it?
The financially savvy traveler — the one who truly grasps what financial freedom means — creates a wallet that’s streamlined, reliable, and refined.
Minimalism isn’t about losing perks. It’s about cutting out unnecessary duplication.
Experian’s official figures show that the typical American holds about four active credit cards.
What’s the issue?
Many of these accounts exist without any clear strategy behind them.
For frequent travelers, this number often rises even further.
The real question isn’t: “How many cards can I juggle?”
It is:
How many cards provide the highest rewards with the least hassle?
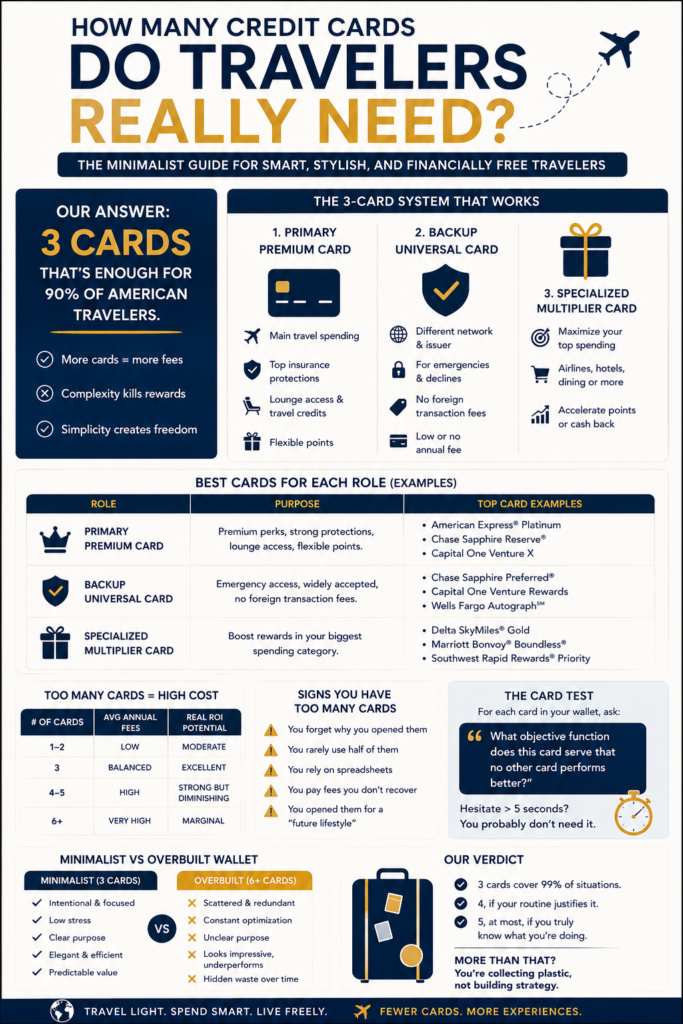
Our editorial recommendation is clear: For 90% of American travelers, three cards suffice.
Here’s the reasoning.
The Hidden Cost of Too Many Cards
| Count of Cards | Typical Annual Fee Burden | Complexity of Management | Actual ROI Potential |
|---|---|---|---|
| 1–2 | Low | Minimal | Moderate |
| 3 | Well Balanced | Low | Outstanding |
| 4–5 | High | Medium | Strong but waning |
| 6+ | Very High | High | Minor gains |
The 3-card system that actually works
The most effective travelers we’ve seen tend to stick with a straightforward setup:
The Intelligent Setup
- One primary premium card
- One universal backup card
- One specialized spending card
This combination handles nearly everything — without clutter, duplication, or unnecessary fees.
Card 1: The powerhouse of your setup
This card drives your international travel and daily spending.
It should include:
- zero foreign transaction fees
- strong travel insurance
- rental car protection
- trip delay and cancellation coverage
- lounge access or meaningful travel credits
- a flexible rewards ecosystem
Currently, three main cards lead the U.S. premium travel market.
American Express Platinum
Great for airport luxury perks. Perfect for travelers who appreciate:
- Centurion Lounge access
- automatic hotel elite status
- aggressive travel statement credits
The catch? Many users pay the annual fee without fully taking advantage of the perks.
If you don’t travel often, this card might not be worth it.
Check out the credit card benefits that truly count with us.
JPMorgan Chase Sapphire Reserve
Arguably the most well-rounded travel card on the market.
- Flexible points.
- Excellent insurance protections.
- Simple redemption mechanics.
- No mental bureaucracy from juggling the Amex ecosystem.
Our take? For most savvy travelers, it offers more practical value than the Platinum card.
Capital One Venture X
Arguably the top premium value card available in the U.S. right now.
It offers high-end perks while keeping management refreshingly straightforward.
If you prefer practical benefits without flashy extras, this card is worth a close look.
Card 2: The essential backup that protects your trips
This card rarely gets featured in lifestyle videos.
Yet it can prevent major problems.
Imagine this:
During a layover in Tokyo, a traveler has their Amex card blocked because of suspicious charges.
A backup card comes to the rescue.
Here’s what your backup card should offer:
| Criteria | Required? |
|---|---|
| Different network | Yes |
| Different bank issuer | Yes |
| No foreign transaction fees | Yes |
| High annual fee | No |
Reliable choices:
- Chase Sapphire Preferred
- Capital One Venture
- Wells Fargo Autograph
This card is about reliability, not prestige.
The difference is important.
Card 3: The strategic multiplier
This card is designed to boost your main everyday spending habits.
Many travelers miss this key point.
They pick aspirational cards. You should focus on cards that fit your habits.
If you spend a lot of time in hotels:
A hotel co-branded card is a smart choice.
If your lifestyle centers on dining out:
Cards with dining rewards pay off.
If your main airline is Delta:
A Delta card can provide great value.
If you frequently fly Southwest:
Southwest Priority might be a smart pick.
But only if it matches your actual habits. Never apply for a card based on the lifestyle you hope to have.
Choose cards that fit the life you truly lead. This is a principle we firmly support editorially.
Check out other recommendations for smart travel cards suited to minimalist lifestyles.
| Warning Sign | What It Indicates |
|---|---|
| You forget the reason you opened some cards | Lack of strategic clarity |
| You seldom use half of your wallet | Unnecessary products |
| You depend on spreadsheets for routine purchases | System complexity is excessive |
| You pay annual fees that you hardly recover | Negative return on investment |
| You opened cards for “future lifestyle goals” | Aspirational overspending habits |
The myth behind the “maximized wallet”
The internet often showcases seven-card lineups. But that can quickly turn into financial cosplay.
It seems impressive. Most of the time, it’s not.
Check the numbers.
| Setup | Typical Total Annual Fees | Extra Real Return |
|---|---|---|
| 3 cards | $400–900 | High |
| 7 cards | $1,500+ | Marginal |
Once you add a third or fourth card, your returns decline steeply. You end up paying for perks you rarely benefit from.
That’s when a credit card stops being a practical tool and turns into a vanity expense.
The test we recommend
Take out your wallet. For each card, ask yourself this:
If it takes you more than five seconds to decide, chances are you don’t really need that card. It’s that straightforward.
Discerning travelers carry fewer cards
Observe seasoned travelers relaxing in lounges at San Francisco International or Miami International airports.
It’s uncommon to find wallets crammed with multiple premium credit cards.
The approach is straightforward:
- Pick your tools with care
- Keep the count low
- Make smart use of each
- That’s elegance in action
There’s real financial wisdom in this approach.
Our final conclusion
If you’re an American traveler focused on efficiency, style, and flexibility in your travel options:
Carry three cards.
- One card to power your lifestyle
- One card to secure your travel freedom
- One card to boost your main spending habits.
Considering more?
In most cases, adding more cards doesn’t actually improve your setup.
You’re just accumulating costly plastic and labeling it a plan.
Keep this in mind!
Keep this image handy and examine it closely to determine if your credit cards genuinely deserve space in your wallet.
FAQ: How Many Credit Cards Should Travelers Actually Carry?